
Don’t miss an episode of our podcast, Personal Finance for Long-Term Investors. Available on all podcast players.
Here’s the latest episode:
Sure, you’ve heard of Senior Citizen discounts. Today’s discount is the opposite.
Shout-out to reader / listener Seth who shared this opinion with me. I’ll paraphrase his thoughts a bit:
When it comes to Social Security claiming, you shouldn’t just discount future dollars using an expected return or time-value-of-money calculation. Instead, you should discount those dollars because the average 62-year-old is a LOT more vibrant than the average 70-year-old.
This is an interesting thought.
Should we consider claiming Social Security earlier to squeeze more life out of it?
Or, put another way, is there a subjective reason why $2000 per month at age 62 is more valuable than $3500 per month at age 70?
And is that subjective reason so powerful that it’s worth locking in those lower payments for life?
…so powerful that it overcomes the objective reasons to delay?
The Objective Baseline
The objective baseline strategy for Social Security is a well-worn discussion. I’ve discussed it at length.
But if we had to rehash the “basic” objective strategy for Social Security claiming, it would be
- Delaying pays. Claiming at 62 permanently cuts your benefit for life. It’s 30% less than if you claim at 67, 44% less than claiming at 70.
- Your health and longevity should drive the decision. The breakeven point for delaying is usually around age 80. If you’re in good health and your family tends to live long, delaying Social Security usually wins. If you have serious health concerns or really need the income now, claiming earlier can make sense.
- Married couples should plan together. When one spouse dies, the survivor keeps the larger of the two benefits. That makes delaying for the higher earner the most valuable move for many couples.
- Coordinate with taxes and your other savings. Up to 85% of your benefits can be taxable, depending on your other income. Many people draw from savings in their 60s as a “bridge” so they can delay Social Security. Those lower-income years can also be a good time for Roth conversions.
So with these clear “rules,” what’s the argument for claiming at age 62?
“Ability to Enjoy It”
In early life, we have health and time, but not much money.
In our middle years, we have more money and health, but not enough time.
As we age, we regain “free time” but start to lose our health.
That’s the simple version, at least.
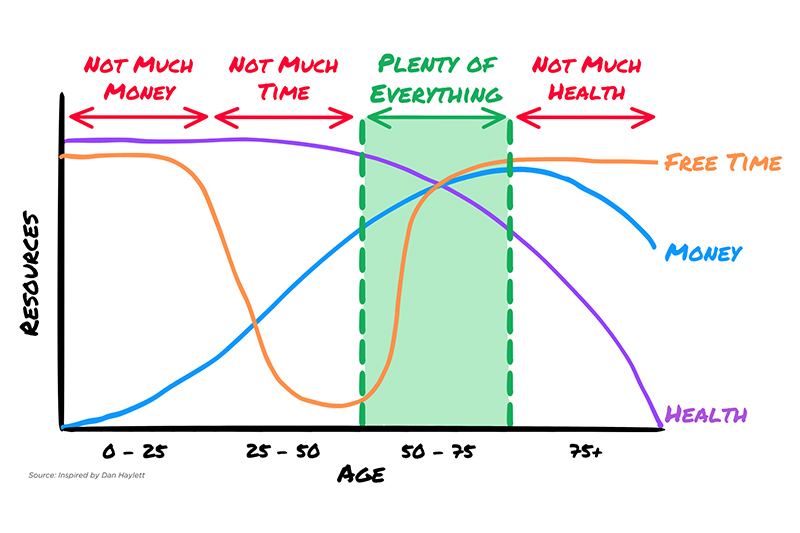
Today’s argument rests on that simple framework.
By the time you’re 70, will you need more money? Will your declining health even let you spend it?
The argument is that traditional, objective Social Security claiming strategies maximize numbers on a spreadsheet, but fall short of a life well-lived.
Whereas claiming early — intending to spend those extra dollars in the more vibrant years of retirement — help maximize the things that truly matter in life.
What say you, reader?
Thank you for reading! Here are three quick notes for you:
First – If you enjoyed this article, join 1000’s of subscribers who read Jesse’s free weekly email, where he send you links to the smartest financial content I find online every week. 100% free, unsubscribe anytime.
Second – Jesse’s podcast “Personal Finance for Long-Term Investors” has grown ~10x over the past couple years, now helping ~20,000 people per month. Tune in and check it out.
Last – Jesse works full-time for a fiduciary wealth management firm in Upstate NY. Jesse and his colleagues help families solve the expensive problems he writes and podcasts about. Schedule a free call with Jesse to see if you’re a good fit for his practice.
We’ll talk to you soon!