

Don’t miss an episode of our podcast, Personal Finance for Long-Term Investors. Available on all podcast players.
Here’s the latest episode:
Small change, giant impact.
One challenge in financial planning is when a “small” decision creates much bigger than we assumed.
“End of Plan” is one such decision. Some planning software might call it “planning horizon” or “life expectancy” or any number of other euphemisms for “when might you die?”
Yes, death is scary to consider.
And it’s obvious how our lifespan affects our finances. The longer we live, the more money we need to live a successful retirement.
But there’s so much more! If you’ve ever dabbled with financial planning software (Boldin, Pralana, eMoney, RightCapital, Empower, etc.), you might be unaware of the unintended side effects that “age at death” is creating in your plan.
Defining the “Problem”…
The (frequent) “problem” I witness follows this logic:
- Running out of money is a scary idea.
- I don’t want to underestimate when we’ll die.
- I’ll overestimate instead…I’ll live until 90. My wife, 95.
- Boom. I’ve “solved” the problem of running out of money.
- [Narrator: But they were completely unaware of the unintended side effects…]
I agree that it’s important to “stress test” whether you’ll run out of money. Changing your assumed age of death is a good idea.
But what else are people missing?
Let’s dive into what people often miss.
Side Effect 1: Social Security Claiming
Extending your End of Plan to age ~85+ almost assuredly pushes your Social Security claiming strategy out to age 70. If you live a long time, you wouldn’t want to claim Social Security early.
This one is straightforward. In fact, it might be less of an “unintended side effect” and more of a “known headliner.”
Plenty of couples should be claiming Social Security before 70 — at least for one of the two spouses.
But if you model your End of Plans out at 85, 90, etc., then the planning software might encourage you both to delay until age 70.
Side Effect 2: Roth Conversions
Roth conversions are tricky. Decades of unknowns lie ahead, and you need to account for them in today’s Roth conversion math. It’s a gray area.
Nevertheless, what’s the effect of assuming someone lives until age 95?
The main effect is that said person would have 20+ years of required minimum distributions, the last of which would be more than 10% of their account value. These RMDs would push this person into higher and higher tax brackets, likely making present-day Roth conversions more and more attractive.
Said succinctly: later death = more Roth conversions today.
But if that same person dies at 75? Roth conversions might be outright bad.
If they die at 80? Perhaps much smaller Roth conversions would be appropriate.
The choice of modeling death at age 85, 90, or 95 can encourage more Roth conversions than otherwise.
Side Effect 3: Widow’s Tax
The “Widow’s Tax” refers to the fact that filing as Single is less preferred than filing Married, Filing Jointly (MFJ), so widows and widowers typically face worse tax treatment than married couples.
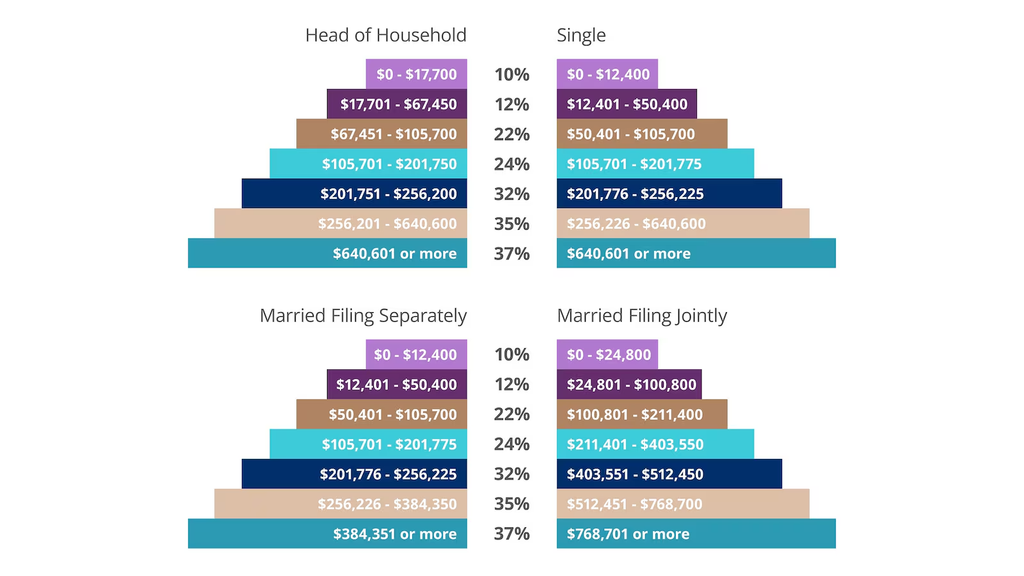
This effect rears its head most when a widow/widower inherits their deceased spouse’s retirement accounts, injecting both spouses’ RMDs into a Single tax return.
It’s natural for a couple to think:
“I’ve got bad health, and I’ll die early. My spouse has good health; they’ll die late. I’ll model my death at 75, their death at 95.”
This decision has massive implications on retirement taxes. By assuming a short span of MFJ years and a long span of Single years, the optimal path would involve injecting extra income (e.g. Roth conversions) into the MFJ years=.
Side Effect 4: Withdrawal Sequencing
The rule of thumb for withdrawal sequencing is taxable first, then tax-deferred, then Roth. But there are plenty of exceptions.
When planning software makes exceptions to this order, it’s typically to smooth income across your tax brackets before RMDs kick in.
The “End of Plan” age directly impacts how your planning engine makes this recommendation. Especially if you decide to model your death in the near-term years.
Side Effect 5: Pension and Annuity Decisions
Pension and annuity decisions are all about “how long will you live?” Plain and simple. Dying at 70 vs. dying at 90 are likely to make “black and white” impacts for what to do with a pension.
I think annuities are oversold and rarely ideal, but when would they be a smart(er) decision? When you live a long life!
In summary, today, how you model your age at death is not just about running out of money. It affects taxes, Social Security, withdrawals, fixed income, and more.
Thank you for reading! Here are three quick notes for you:
First – If you enjoyed this article, join 1000’s of subscribers who read Jesse’s free weekly email, where he send you links to the smartest financial content I find online every week. 100% free, unsubscribe anytime.
Second – Jesse’s podcast “Personal Finance for Long-Term Investors” has grown ~10x over the past couple years, now helping ~20,000 people per month. Tune in and check it out.
Last – Jesse works full-time for a fiduciary wealth management firm in Upstate NY. Jesse and his colleagues help families solve the expensive problems he writes and podcasts about. Schedule a free call with Jesse to see if you’re a good fit for his practice.
We’ll talk to you soon!