
This decade, wine commentators have incessantly bemoaned both wine’s ‘dwindling allure’ amongst younger drinkers, and the phenomenon of falling sales more broadly. Naysayers hypothesise all manner of causes, ranging from wine being stuffy and elitist, to sluggish innovation, failing to connect with the values of younger drinkers, and a lack of ‘inclusivity’—which has been a prominent preoccupation of many working in wine since at least 2020. Notably, it is commonplace to portray wine’s ailments as autogenous, brought about by a failing industry occupied by anachronistic gatekeepers. Concomitantly, a host of emerging online personalities have positioned themselves as ideally placed to cure wine’s ailments, making it more accessible and unlocking a lucrative younger audience the industry has apparently failed to attract.
The truth is much more sobering; wine’s meteoric ascent beginning in the 1970s, and accelerating dramatically from the mid-1990s, was not of its own doing; instead, it was the result of favourable socioeconomic circumstances and sweeping technological, commercial, and industrial changes, resulting in wine capturing a significant portion of gross increases in alcohol consumption. Similarly, falling sales are equally attributable to significant social, cultural and demographic change, this time distinctly unfavourable for wine sales, which, despite apparent strength, were uniquely fragile. Examining this rise and fall in more detail may help temper reactionary reflexions and give hope to those rooting for fine wine.

Until 1962, despite the English having imported wine for centuries, consumption in litres of alcohol per head was low, far exceeded by both beer and spirits. Before this time, wine consumption was also highly unequal, largely confined to the court, aristocracy, clergy, and wealthy merchants, and later the urban and elite classes. Compared to wine, beer and ale were much cheaper, more calorific, and framed positively by the state as English, wholesome, and patriotic. In contrast, wine was a symbol of refinement and foreignness, and taxed heavily—even when duties fell, wine did not penetrate everyday life the way beer did.
Then, in the sixties, a cluster of structural changes made wine more available, affordable, attractive, and accessible for ordinary people, beginning with changes to retail licensing laws allowing supermarkets to begin selling alcohol. Ten years later, supermarket wine sales had grown from 5% of off-trade wine, beer and spirits to 25%. This staggering expansion was largely attributable to Sainsbury’s, Tesco, Waitrose and the Co-Op, who were first to exploit an aspirational middle class increasingly preoccupied with continental luxuries. This preoccupation was exaggerated by Common Market membership in 1973, which also marked the genesis of own-label supermarket wines.
Having made wine more available to ordinary shoppers, supermarket sales benefited from changing socioeconomic conditions and consumer preferences. From the mid-1950s to the late 1960s, foreign travel roughly tripled from about 2 million to nearly 6 million trips per year as air packages to sunny destinations grew increasingly popular, coupled with more paid leave and rising living standards, giving the growing middle class more time and money to travel.
All this meant more Brits experienced wine in continental Europe, where it was enjoyed unpretentiously with dinner and lunch. These new experiences softened longstanding, rigid class obstacles, helping wine cease being a test of stock and instead become a matter of mere preference for all who enjoyed it. All this was further catalysed by evolving cookery culture in print media and on television, including the rise of popular chefs and personalities who introduced new recipes featuring wine and reintroduced continental cooking techniques. From this, wine begins its transformation from ingredient to accompaniment, and increased interest in cooking begins to shift drinking from the pub to home, where wine drinking becomes civilised domestic consumption enjoyed equally by both sexes.
Following this first inflection, the 1990s saw a second explosion in wine consumption, after which wine stopped being adopted and began to be industrialised, routinised, and financially engineered in the UK. By this time, supermarkets had systematically commercialised wine sales, dedicating wine buyers with immense global sourcing power who not only centralised contracts with producers but also implemented own-label wine at scale, leveraging new technologies to improve accessibility and reduce pricing. Notably, this era comes with the emergence of mass industrial wine priced painfully cheap (£3.99-£5.99), all made possible by bulk shipping, commercial winemaking practices, southern hemisphere harvest counter-cyclicality, and global blending. It is during this same period that New World wines achieve critical mass. By 1996, Australia had overtaken France as the largest supplier of wine to the UK off-trade market. And by 2000, Chile, Argentina, South Africa, and New Zealand were all surging in popularity, heavily promoted by supermarkets through new own-label partnerships and exclusive import deals.
These evolving ranges coincide with the transformation of supermarkets from general retailers to sprawling one-stop shops, ravaging traditional, specialist retailers like butchers, greengrocers, and off-licences, consolidating disparate shopping trips into single weekly supermarket visits, and permanently changing the nature of English high streets. Consequently, by 2012, supermarkets accounted for a staggering 81% of off-trade wine sales. The same supermarkets, benefitting from economies of scale, also introduced sweeping promotional mechanics, often offering wine so cheap it served as a ‘loss-leader’, intended to boost sales of complementary items, or undercut independent retailers traditionally favoured by target buyers. These falling prices and promotional offers were made even more attractive by rising pub prices and, later, the smoking ban, which helped shift drinking even further toward the home.
Following the increased regularity of wine drinking, this period marks the beginning of marked overconsumption, encouraged by supermarkets that leveraged greater EU integration, stable tariffs and predictable logistics. Similarly, European exporters took advantage of England’s dramatically increasing consumption, using the market as a pressure valve for continental oversupply, enabling supermarkets to maintain low prices even as quality increased. Various other socioeconomic, political and technological conditions also helped stimulate wine sales, including increasing internet access, including wine advice and forums, and more wine columns in print media.
Perhaps most importantly, in the 1990s, the buyers who first adopted wine en masse in the 1970s came of age, entering their peak earning years and setting up homes, buying weekly groceries at local supermarkets, and hosting dinners with friends, all of which now regularly featured wine as normal course. By the mid-2010s, wine’s success was staggering, and as beer sales fell, it almost became the most popular alcoholic beverage with English drinkers. And, whilst retailers and merchants did capitalise on this growing success, wine’s stratospheric growth can be largely attributed to the convergence of various structural changes which brought about the perfect circumstances for a staggering boom.

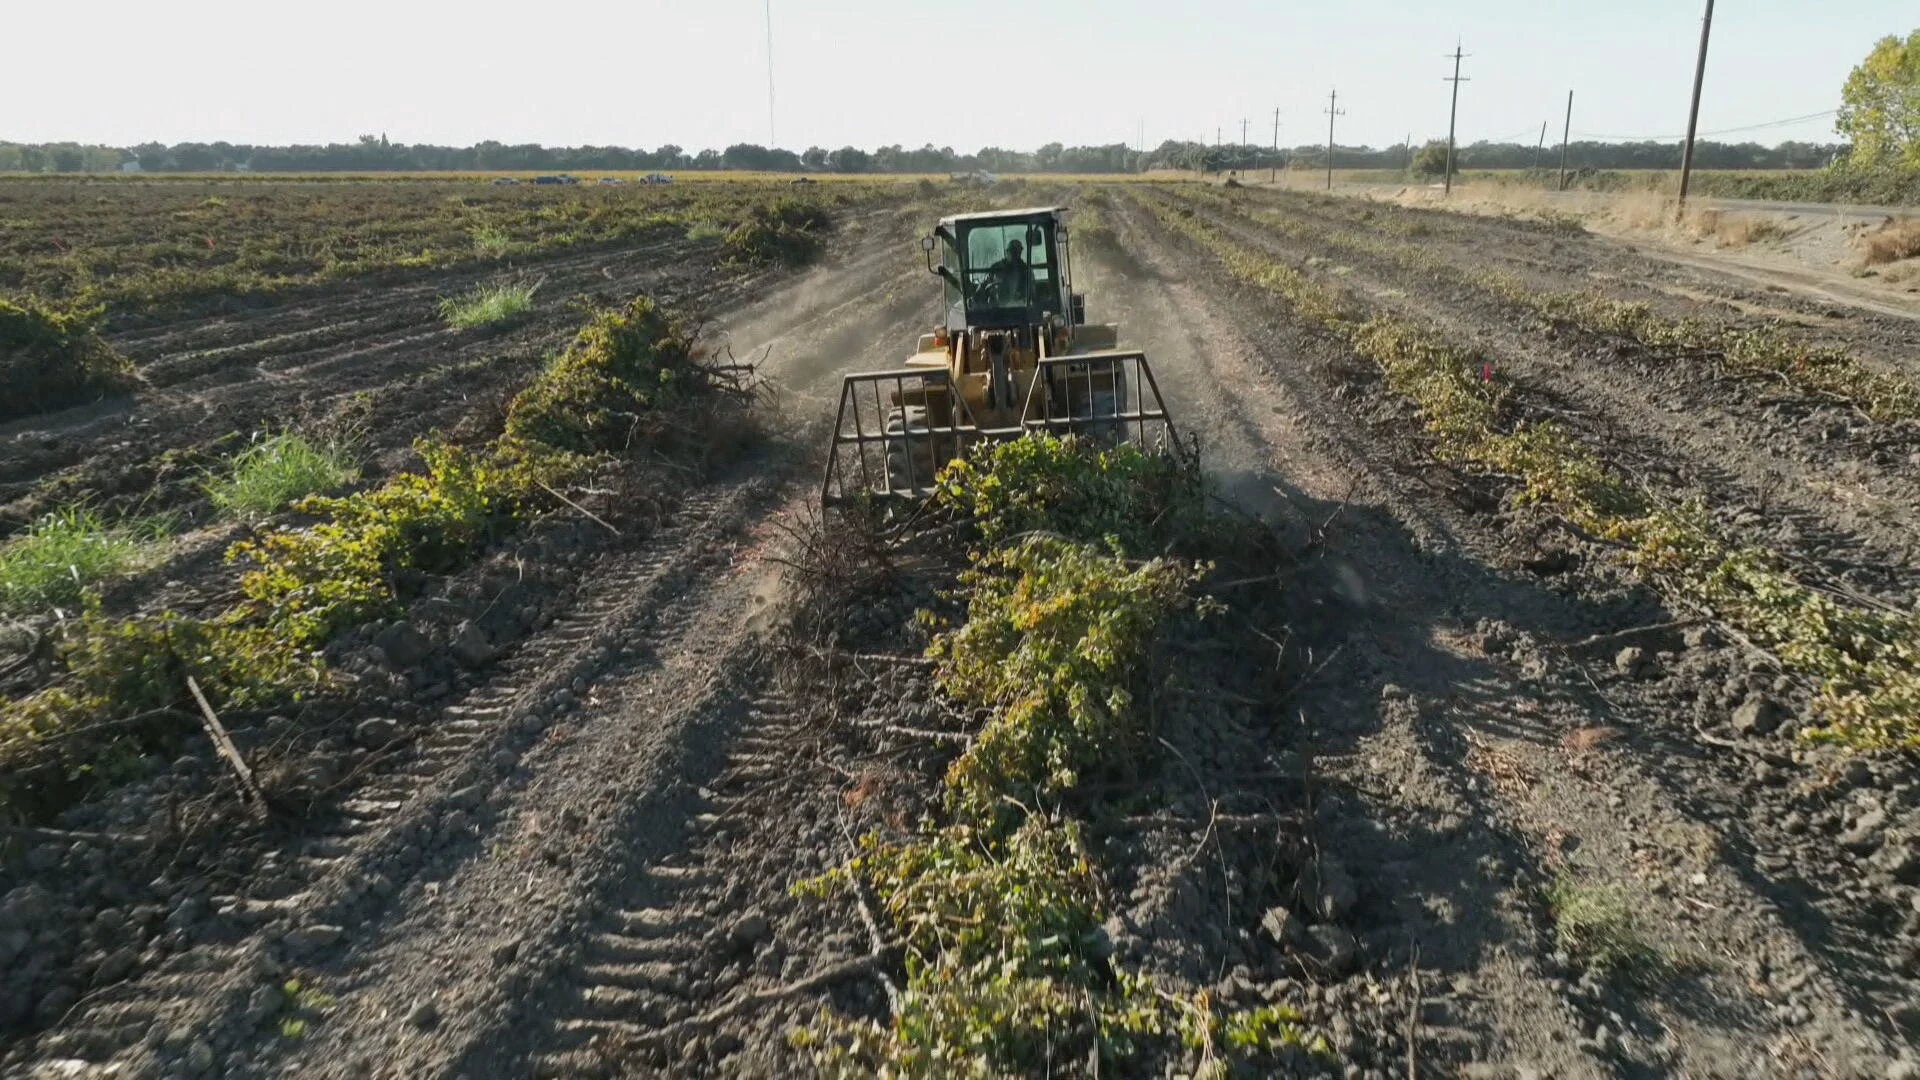
In sharp contrast, per capita consumption is now declining, and wine sales and imports are falling sharply. Despite a great deal of the explanations offered for this fall attributing blame to a failing industry in desperate need of fresh, diverse voices to unlock a lucrative Millennial and Gen Z audience, the truth is arguably more concerning. Wine sales are falling because the system that created overconsumption has broken, and the factors conducive to its post-1970 boom are now dead set against it, and more.
Critically, the demographic engine driving wine’s growth no longer favours its success; the cohort present during wine’s meteoric rise, who drank and bought the most wine, and drank habitually at home, are now, for one reason or another, drinking less wine. Conversely, their children and grandchildren were not subject to the same frenzy for wine as their elders, and so aren’t nearly as inclined to consume it. This same cohort also remains living at home for much longer and is much less likely than Boomers or Gen X to start a family early, thus they are not regular hosts or food shoppers.
Another significant demographic transformation has taken place in England during the past three decades, which is also unfavourable for wine. As of 2021, only 74% of people living in England and Wales identified as White British, compared to over 93% in the early 1970s. A significant proportion of this demographic change is attributable to migration and consists of low-income, non-EU nationals—since 2021, low-skilled non-EU migration has become the majority driver of UK immigration. It is an insurmountable fact that a large portion of these people do not and will not consume wine; this is true for varying reasons, ranging from cultural indifference to religious permissibility. Ironically, despite the wine industry being lambasted for being ‘too white’, and popular personalities demanding wine ‘embrace diversity’, a great paradox is whether diversity can, in fact, embrace wine and what impact dramatic demographic changes—white Brits could slip below 50% around the early-to-mid 2060s—could have on its future.
Next, following subtle changes in diet, exercise and work during the previous decade, health and ‘wellness’ culture booms in the noughties; low-fat diets, early wearable tech and self-help and productivity culture result in growing tension between alcohol and performance and wellbeing. This tension became explicit this past decade with the onset of growing mental health discourse; longevity, health and performance commentary; and increasing numbers of people committing to serious fitness pursuits. From this, alcohol is increasingly related to poor physical and mental health (including cancers), diminished sporting and work performance, and unfavourable societal and environmental conditions. Importantly, these trends recently coalesced with a growing and explicit anti-alcohol sentiment within supranational organisations like the World Health Organisation, whose recommendation that there is no safe level of alcohol consumption appears to have been influenced by neo-prohibitionist temperance movements. Sadly, this fall in alcohol consumption has distinctly damaged wine, which depends largely on cheap, frequent consumption and has no good low-alcohol substitutes. And, just as tea, coffee and sugar damaged small beer and spirits sales in Georgian London, today, non-alcoholic beers, functional drinks, and premium soft drinks are chosen over alcohol by many conscious consumers.
The unsettling reality of all this is that falling wine sales are both inevitable and unstoppable. Just as a series of structural changes ushered in wine’s phenomenal past growth, a similarly impactful series now impedes it. But all is not lost, falling total sales mask great hope for wine lovers. Whilst supermarket wine sales are down, sales of bottles worth £17.78 to £33.75 are up; younger drinkers are giving up on cheap, industrial junk, opting instead for craft, artisan wines made by thoughtful growers and sold by passionate independents or in their favourite restaurants and bars.
In London, bars like Lower, 10 Cases and Crispin humbly present the world’s most exciting wines in approachable settings. Further north, the country’s first champagne boutique serves grower champagne to youthful crowds in Manchester’s metropolitan centre. And in Birmingham, new restaurant Trillium pairs great food with a 28-page wine list and 30 wines by the glass served by a growing wine team. Elsewhere, passionate sommeliers introduce inquisitive guests to emerging producers alongside classic greats at the country’s very best restaurants, like Rory Eaton at Ynyshir and Grace Cox at The Barn. Nothing elucidates the changing preferences of younger drinkers more, though, than the runaway success of emerging fine winegrowers in both established and unsuspecting regions—regions like Tenerife have experienced huge growth in demand for fine wines from curious buyers globally. Similarly, the merchants promoting these producers are experiencing equal success; the most recent Keeling Andrew portfolio tasting was packed wall-to-wall with eager drinkers, young and old. Overseas, like-minded merchant Thatcher Baker-Briggs reports that in 2025, 92% of his customers were new buyers, accounting for more than four prior years in business.
A tertiary glance at falling wine sales can be alarming, and without proper scrutiny, can make repeated claims about the wine industry’s many ‘failings’ appear legitimate. However, the truth is that for two decades, wine has been battered by adverse forces unfavourable to alcohol, and in many cases uniquely hostile to wine. Upon closer examination, this unfavourable tide is primarily stacked against industrial wine, ending the scourge of supermarket wine despite the best efforts of hapless vinfluencers peddling bargain basement plonk. It is hopeless to imagine reversing such implacable forces; instead, wine lovers should ditch the bogus supermarket-to-collector-pipeline theory, embrace the merits of changing preferences and seize the opportunity to promote and prioritise quality, living wines. In such a world, the future of wine is bright, albeit markedly smaller.