
Quick Summary: A single catastrophic health insurance claim can cost a self-funded employer hundreds of thousands of dollars. The employers who manage those costs without destabilizing their plans have built the right structure and activated the right strategies before the diagnosis arrives.
A single catastrophic diagnosis can reshape an employer’s entire claims year. Cancer treatment, organ transplants, premature births, and heart failure generate high, extended costs that a routine claims year can’t absorb.
For self-funded employers, this is one of the most important things to understand before making the move away from fully insured coverage. The exposure is real, but the protection is also real, provided your plan is structured to handle it.
What Qualifies as a Catastrophic Diagnosis?
A catastrophic diagnosis is any condition that is life-threatening or likely to result in long-term disability. Common examples include:
- Cancer (the leading catastrophic claims condition for self-funded employers)
- Kidney failure
- Heart attack and stroke
- Organ transplant
- Premature birth
- Sepsis
- Major burns and postsurgical complications
- Paralysis
These conditions generate costs well above normal claims thresholds through inpatient hospitalization, surgical procedures, infused or specialty medications, and long recovery timelines that often produce additional medical issues.
According to KFF research, the top 5% of patients account for roughly half of all health spending. For self-funded employers paying claims directly, that concentration is where plan performance is won or lost.
Top Catastrophic Claims Conditions for Self-Funded Employers
| Condition | Share of Stop-Loss Claims | Notes |
|---|---|---|
|
Cancer (malignant neoplasms)
|
No. 1 for 10+ consecutive years
|
Generated $1.2B across ~5,000 claims in 2024
|
|
Cardiovascular conditions
|
No. 2
|
Costs roughly one-third of cancer spend
|
|
Conditions affecting newborns/premature birth
|
Top 5
|
Consistent top driver year over year
|
|
Transplant-related conditions
|
Top 5
|
Increasing as procedures become more complex
|
|
Sepsis
|
Top 10
|
Compounding costs from extended hospitalization
|
|
Musculoskeletal (complex surgeries)
|
Top 10
|
Second costliest condition by large margin
|
How Self-Funded Employers Protect Against Catastrophic Claims
The financial protection built into a self-funded group captive plan is what makes it possible for companies to manage catastrophic claims without absorbing the full cost alone.
Stop-loss insurance sets a specific deductible for individual high-cost claimants, typically $50,000 to $100,000 per employee. Once a member’s claims exceed that threshold, the stop-loss carrier covers the remainder. This converts an open-ended liability into a number you can plan around.
In Roundstone’s group captive, risk pooling adds another layer. When a member company has a catastrophic claim that falls within the shared pool layer, the captive absorbs it across hundreds of participating employers.
One cancer diagnosis or premature birth doesn’t fall entirely on one employer’s plan; the structure is designed specifically to prevent that. Stop-loss reinsurance then covers claims above the pool at the top end.
Stop-loss and captive risk pooling are the financial backstop of a self-funded plan. The cost-containment strategies below are how employers use plan design and clinical support to manage costs within that protected structure.
How Do Self-Funded Employers Contain Catastrophic Diagnosis Costs?
1. Prioritize Primary Care
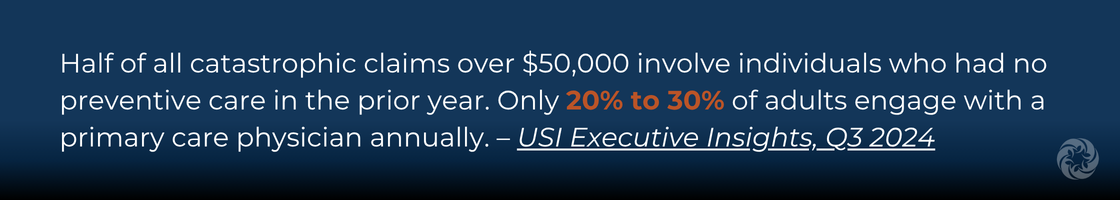
The best cost-containment strategy for catastrophic illness is catching problems before they become catastrophic. Regular preventive visits and screenings are what make that possible.
When primary care physicians detect a developing condition early, treatment is less complex, less expensive, and more likely to succeed. The most effective way to encourage this behavior is to remove financial barriers.
Employees are more likely to schedule routine screenings when there are no copays and no deductibles for preventive care, and that investment pays off well before a major diagnosis appears.
2. Use Prior Authorization and Case Management
When a member’s health situation escalates, prior authorization triggers the case management process. A TPA trained in clinical case management steps in to coordinate care, verify that the member is receiving appropriate treatment, and identify the most cost-effective pathway forward.
This process is valuable at every stage. Pre-authorization for screenings like mammograms or colonoscopies keeps routine care on track. When results are abnormal, that same authorization process flags the case for closer oversight, putting the right specialists on the case before treatment decisions get made.
Case management reduces duplicate testing, prevents unnecessary procedures, and keeps the member informed throughout a complex treatment journey.
3. Build Second Opinions Into the Plan
A second opinion is one of the most cost-effective tools available for high-cost diagnoses. Research published in Mayo Clinic Proceedings found that up to 88% of second opinions for serious medical conditions result in a major change to the diagnosis or recommended treatment plan. Cleveland Clinic data puts the diagnosis change rate at 28% of cases reviewed.
The financial implications are significant. When initial care recommendations exceeded $10,000, Cleveland Clinic’s virtual second opinion program saved more than $100,000 per patient on average. Getting the right diagnosis early means avoiding the cost of treating the wrong condition, and that scenario is more common than most employers expect.
For elective procedures and high-cost treatment decisions, a structured second-opinion program directed toward high-volume, high-quality providers produces better outcomes and lower total costs.
Second Opinion Outcomes by the Numbers
| Metric | Finding | Source |
|---|---|---|
|
Diagnosis or treatment change rate
|
88% of second opinions for serious conditions result in a major change
|
Mayo Clinic Proceedings
|
|
Diagnosis change rate (Cleveland Clinic)
|
28% of cases result in a new diagnosis
|
Cleveland Clinic / Amwell
|
|
Treatment plan modification rate
|
67% of virtual second opinions lead to diagnosis or treatment adjustments
|
Cleveland Clinic / Amwell
|
|
Surgery avoided
|
Recommended less invasive alternative 85% of the time when surgery was initially planned
|
The Clinic by Cleveland Clinic
|
|
Average health plan savings per case
|
$8,705 per case on average
|
Amwell / Cleveland Clinic
|
|
Savings on high-cost cases (initial cost >$10K)
|
More than $100,000 saved per patient on average
|
The Clinic by Cleveland Clinic
|
Sources: Mayo Clinic Proceedings via Employee Benefit News | Amwell / Cleveland Clinic | Fierce Healthcare, April 2024
4. Access a Center of Excellence Network
A Center of Excellence (COE) is a specialized provider or facility that focuses on specific high-cost conditions and procedures, with a track record of strong outcomes at predictable costs. Transplants, cancer treatment, complex cardiac procedures, and orthopedic surgeries are among the areas where COE networks deliver the most consistent savings.
Roundstone partners with COE networks that connect captive members to the right provider or surgical team, reduce time on waitlists, and ensure members understand their treatment options. These networks offer fixed-price contracts for specific procedures, removing the cost unpredictability that makes catastrophic claims difficult to plan around.
Better care leads to fewer complications, shorter hospital stays, and lower long-term costs. Quality and cost efficiency point in the same direction.
Center of Excellence Impact on Costs and Outcomes
| Metric | Finding | Source |
|---|---|---|
|
Average employer savings per procedure
|
$16,144 per surgery (bundled payment model)
|
RAND Corporation study via Carrum Health
|
|
Readmission reduction
|
80% fewer readmissions for joint replacement, spinal fusion, and bariatric surgery
|
RAND Corporation / Carrum Health
|
|
COE adoption for cancer (large employers)
|
53% offering cancer-focused COE in 2024; 23% considering by 2026
|
Business Group on Health, 2024
|
|
Employers considering COE requirements
|
42% would strongly consider requiring COE use to reduce costs
|
Lantern 2025 Employer Healthcare Strategy Survey
|
|
Overall cost reduction
|
COEs can lower employer costs by more than 10%
|
KFF / Mployer Advisor, 2025
|
|
Oncology share of employer health spend
|
Cancer accounts for 15% of overall employer health spend but only 1% of claim volume
|
Mahoney Group
|
Sources: Carrum Health / RAND | Business Group on Health, 2024 | Lantern 2025 Survey | Mployer Advisor, 2025
5. Support Survivorship
Preventing a catastrophic diagnosis from becoming a long-term cost driver requires a plan that doesn’t stop at discharge. Survivorship guidelines, the post-treatment protocols for conditions like cancer or organ transplant, are designed to monitor patients, catch complications early, and prevent rehospitalization.
Educating members about survivorship expectations and building follow-up care into the plan design reduces the risk of readmission, new diagnoses, and the costs that often follow a major health event. Cancer patients face statistically higher risk of new cancer diagnoses after treatment. Consistent follow-up screening is effective cost containment and sound clinical practice at the same time.

One Catastrophic Claim Will Test Your Plan
The employers who manage high-cost diagnoses most effectively have stop-loss coverage, captive risk pooling, and clinical case management already in place before a serious diagnosis appears. Roundstone’s group captive builds that foundation into the plan from day one.
Talk to a Roundstone rep today to see how your current plan measures up.
Frequently Asked Questions
What is a catastrophic diagnosis for health insurance purposes?
A catastrophic diagnosis is a life-threatening condition or one expected to cause long-term disability. Cancer, kidney failure, organ transplant, heart attack, stroke, premature birth, and sepsis are among the most common. These conditions generate sustained, high-cost claims through hospitalization, surgical procedures, and specialty medications.
How do self-funded employers protect against catastrophic claims?
Self-funded employers use stop-loss insurance to cap their exposure on individual high-cost claimants. In a group captive like Roundstone’s, risk pooling across hundreds of employers adds a second layer of protection before stop-loss insurance kicks in, making catastrophic claim costs predictable and manageable.
What medical conditions generate the most catastrophic claims for employers?
Cancer is the leading catastrophic claims condition for self-insured employers, accounting for roughly 25% of stop-loss reimbursements according to Sun Life Financial research. Other top conditions include premature birth, congestive heart failure, organ transplant, stroke, sepsis, and complications from major surgeries.
What is a Center of Excellence and how does it reduce costs?
A Center of Excellence is a specialized provider or facility that handles specific high-cost procedures with consistently strong outcomes. COE networks steer plan members to the right provider, often with bundled pricing, shorter wait times, and lower complication rates. Better outcomes mean fewer readmissions, shorter recoveries, and lower total claim costs.
Can a single catastrophic claim destabilize a self-funded plan?
Without the right structure, yes. That’s why stop-loss insurance and group captive risk pooling exist. In a properly structured captive plan, no single member’s catastrophic diagnosis falls entirely on one employer. The financial risk is distributed and capped, so one difficult claims year doesn’t undermine the plan.
Does a self-funded plan cover catastrophic diagnoses the same way fully insured plans do?
Self-funded plans can be designed to provide comprehensive coverage for catastrophic conditions. Employers in a group captive have the flexibility to build cost-containment strategies into their plan design and maintain strong coverage for members facing serious illness, two outcomes that are difficult to achieve simultaneously in a fully insured arrangement.
{“@context”:”https:\/\/schema.org”,”@type”:”FAQPage”,”mainEntity”:[{“@type”:”Question”,”name”:”What is a catastrophic diagnosis for health insurance purposes?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”A catastrophic diagnosis is a life-threatening condition or one expected to cause long-term disability. Cancer, kidney failure, organ transplant, heart attack, stroke, premature birth, and sepsis are among the most common. These conditions generate sustained, high-cost claims through hospitalization, surgical procedures, and specialty medications.”}},{“@type”:”Question”,”name”:”How do self-funded employers protect against catastrophic claims?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Self-funded employers use stop-loss insurance to cap their exposure on individual high-cost claimants. In a group captive like Roundstone’s, risk pooling across hundreds of employers adds a second layer of protection before stop-loss insurance kicks in, making catastrophic claim costs predictable and manageable.”}},{“@type”:”Question”,”name”:”What medical conditions generate the most catastrophic claims for employers?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Cancer is the leading catastrophic claims condition for self-insured employers, accounting for roughly 25% of stop-loss reimbursements according to Sun Life Financial research. Other top conditions include premature birth, congestive heart failure, organ transplant, stroke, sepsis, and complications from major surgeries.”}},{“@type”:”Question”,”name”:”What is a Center of Excellence and how does it reduce costs?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”A Center of Excellence is a specialized provider or facility that handles specific high-cost procedures with consistently strong outcomes. COE networks steer plan members to the right provider, often with bundled pricing, shorter wait times, and lower complication rates. Better outcomes mean fewer readmissions, shorter recoveries, and lower total claim costs.”}},{“@type”:”Question”,”name”:”Can a single catastrophic claim destabilize a self-funded plan?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Without the right structure, yes. That’s why stop-loss insurance and group captive risk pooling exist. In a properly structured captive plan, no single member’s catastrophic diagnosis falls entirely on one employer. The financial risk is distributed and capped, so one difficult claims year doesn’t undermine the plan.”}},{“@type”:”Question”,”name”:”Does a self-funded plan cover catastrophic diagnoses the same way fully insured plans do?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Self-funded plans can be designed to provide comprehensive coverage for catastrophic conditions. Employers in a group captive have the flexibility to build cost-containment strategies into their plan design and maintain strong coverage for members facing serious illness, two outcomes that are difficult to achieve simultaneously in a fully insured arrangement.”}}]}
Managing Catastrophic Diagnoses Starts With the Right Plan Structure
Employers who manage catastrophic claims most effectively aren’t just reacting when a serious diagnosis appears. They’ve built a plan with stop-loss coverage at the right threshold, captive risk pooling to absorb mid-range exposure, and a TPA with clinical case management capabilities already in place.
Roundstone’s group captive brings all of these elements together so that when a high-cost diagnosis does occur, you have the structure, the clinical support, and the financial protection to respond without it defining your year.
The post 5 Cost-Containment Strategies Self-Funded Employers Use to Manage Catastrophic Diagnosis Costs appeared first on Roundstone Insurance.